

Haemonetics has been on fire lately. In the past six months alone, the company’s stock price has rocketed 96.3%, reaching $118.21 per share. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy Haemonetics, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Haemonetics Not Exciting?
Despite the momentum, we’re passing on Haemonetics for now. Here are three reasons why HAE doesn’t excite us, plus one stock we’d rather own.
1. Revenue Growth Flatlining
Long-term growth is the most important, but within healthcare, a stretched historical view may miss new innovations or demand cycles. Haemonetics’s recent performance shows its demand has slowed as its revenue was flat over the last two years. 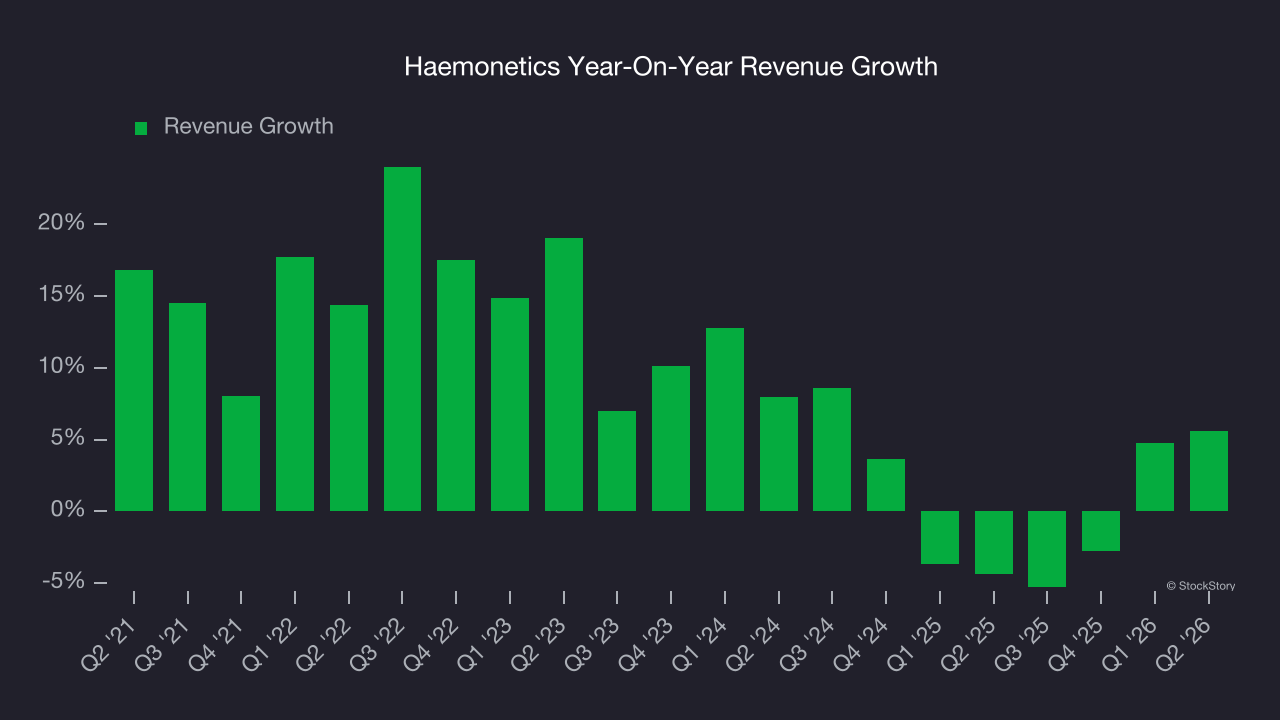
2. Slow Organic Growth Suggests Waning Demand In Core Business
Investors interested in Medical Devices & Supplies - Specialty companies should track organic revenue in addition to reported revenue. This metric gives visibility into Haemonetics’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, Haemonetics’s organic revenue averaged 3.2% year-on-year growth. This performance slightly lagged the sector and suggests it may need to improve its products, pricing, or go-to-market strategy, which can add an extra layer of complexity to its operations. 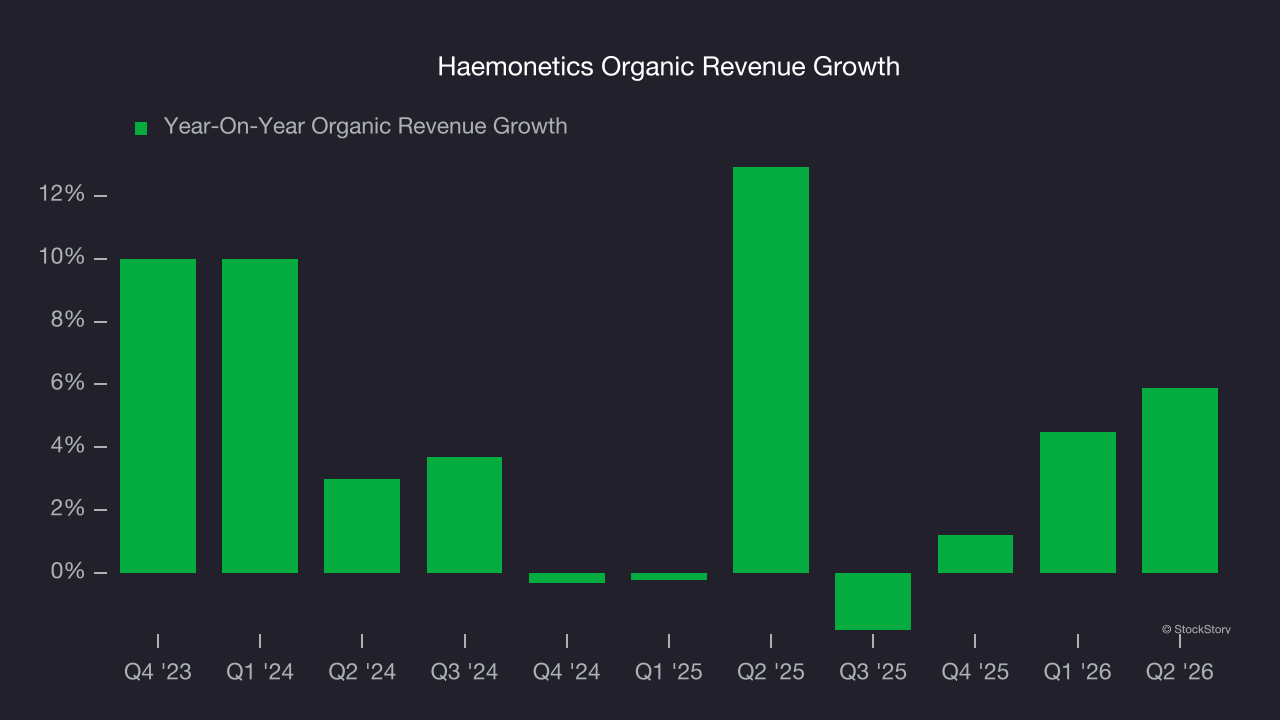
3. Fewer Distribution Channels Limit Its Ceiling
Larger companies benefit from economies of scale, where fixed costs like infrastructure, technology, and administration are spread over a higher volume of goods or services, reducing the cost per unit. Scale can also lead to bargaining power with suppliers, greater brand recognition, and more investment firepower. A virtuous cycle can ensue if a scaled company plays its cards right.
With just $1.35 billion in revenue over the past 12 months, Haemonetics is a small company in an industry where scale matters. This makes it difficult to build trust with customers because healthcare is heavily regulated, complex, and resource-intensive.
Final Judgment
Haemonetics isn’t a terrible business, but it doesn’t pass our bar. Following the recent surge, the stock trades at 21.5× forward P/E (or $118.21 per share). Investors with a higher risk tolerance might like the company, but we think the potential downside is too great. We’re fairly confident there are better investments elsewhere. Let us point you toward the most entrenched endpoint security platform on the market.
Stocks We Like More Than Haemonetics
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.